Honda Jazz Finance & APR Calculator
Thinking about financing a Honda Jazz? But you're unsure if the dealer's finance quote is competitive?
Let Prefinance help. Tell us the exact Jazz you're looking at, and we'll compare the dealer's own finance example against the best rate our panel of brokers can offer on that kind of car. Averaged across every comparison we've run, that's a saving of up to 30% against dealer finance; an average across many deals rather than a promise attached to yours, and a good number of dealers quote fairly from the start.
Honda Jazz finance quotes
Rates and calculations correct at time of posting but are subject to change.
Vehicle | Cash price | Deposit | Amount of credit | Term | Rep. APR | Monthly payment | GFV / Final payment | Monthly savings vs dealer | Finance type* |
|---|---|---|---|---|---|---|---|---|---|
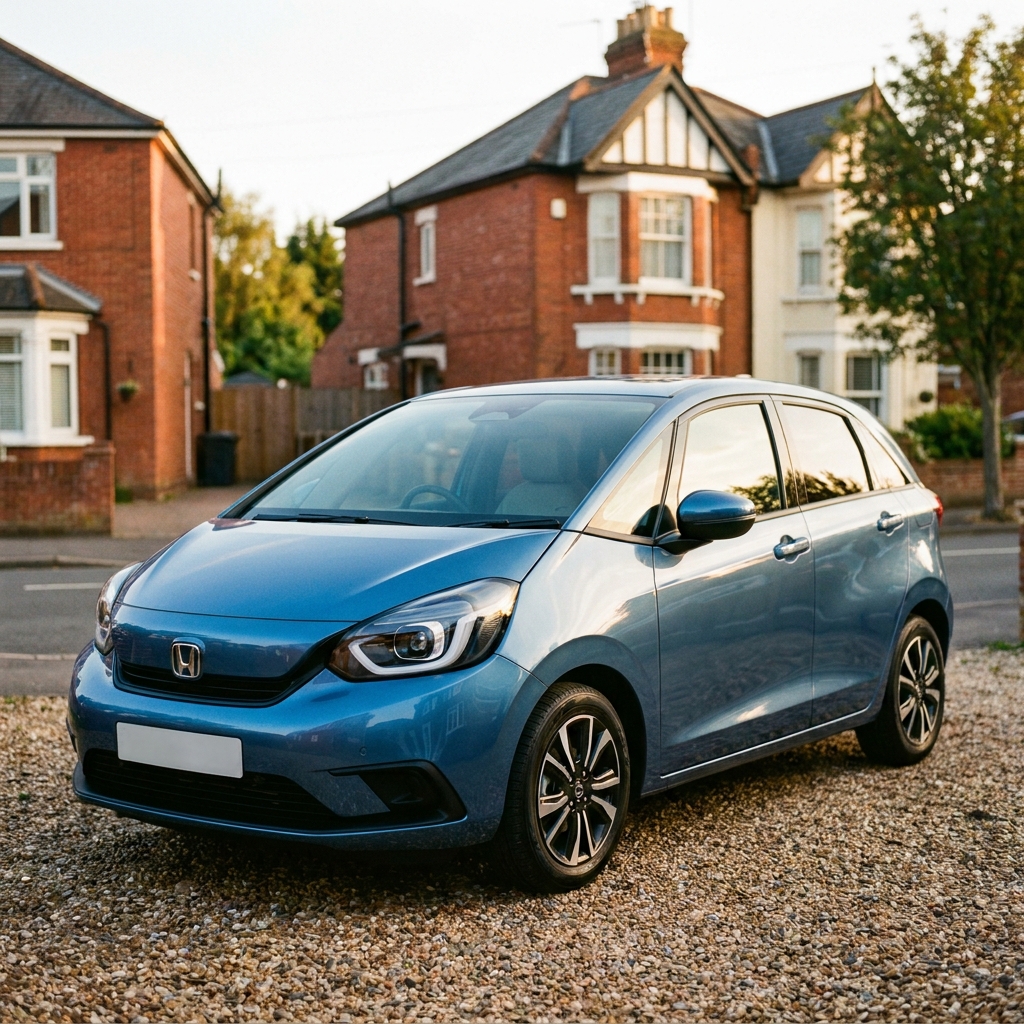
2026 Jazz, 3,000 miles (quoted 30 Sep 2026) | £24,990 | £2,509 | £22,481 | 48 months | 8.9% | £363.56 | GFV £11,259.77 | £54.23 | PCP |
2025 Jazz, 5,594 miles (quoted 30 Sep 2026) | £24,699 | £2,470 | £22,229 | 48 months | 8.9% | £341.79 | GFV £12,123 | £36.81 | PCP |
PCP or HP: what these quotes are, and what they aren't
Both structures count as hire purchase in law, with the lender keeping ownership until the final payment goes through. How they differ is in what your monthly payments are buying. HP (Hire Purchase) spreads the price less deposit evenly across the term, with every instalment moving you toward owning the car. PCP (Personal Contract Plan) sets a Guaranteed (Minimum) Future Value aside, due only if you decide to keep the car at the end, and that deferred amount is what holds the monthly figure down. Both Jazz quotes are PCP, deferring £11,259.77 and £12,123 respectively; which is to say roughly half of each car's price is waiting at the end rather than being paid off along the way.
One assumption underpins the instant comparison, whichever structure you choose: we take the dealer's GFV as the figure your matched lender would apply. Given how much of the monthly payment rests on that number here, a broker who sets it differently will move your real payment noticeably.
Where the saving comes from
Three ways to start: a registration number, a make and model, or a link pasted from a dealer's site or a listings site such as Autotrader — that last route working only if the page carries a finance example. We read the dealer's quote from it and compare it against the strongest rate our broker panel holds for that class of car. The result assumes your credit profile would secure the panel's best rate, and that the dealer selling the car is FCA authorised. Every comparison stays on your account for you to return to.
Representative APR has a defined meaning: at least 51% of the customers a provider approves receive that rate or better. A benchmark, then, rather than an offer to you specifically.
What moves the number you're quoted
Your credit profile carries the most weight, with deposit, term and GFV behind it. The Jazz pair is a reminder that the GFV can matter more than the price: two cars £291 apart produced payments £21.77 apart, and the direction of that gap was set by the GFV rather than by which car cost more. Age and mileage feed into how a lender sets that figure, though as these two show, not always in the direction you'd predict. A longer term lowers the monthly payment while raising the total interest paid.
Commission deserves a mention as well. Putting finance together earns both dealers and brokers a payment, and that payment forms part of the rate you're offered; one genuine reason two buyers can be quoted differently on near-identical cars. Bringing that gap into the open is much of what the comparison does.
Worth checking before you sign
Check the deposit and mileage in your comparison against what the dealer has actually quoted; the deposit is yours to change, but any other mismatch distorts the result.
Ask what GFV your agreement is built on, and what the monthly payment becomes if your matched lender sets a different one — on a Jazz, roughly half the price can be riding on that figure.
Where two similar cars carry different GFVs, as the pair above do, ask what's behind it before assuming the cheaper monthly payment is the better deal.
If you want to own the car outright at the end, ask about HP terms, since neither live quote is structured that way.
Read the broker's full representative example before signing anything; your deal's real numbers are there, not in the illustrative figures above.
None of this tells you upfront whether the dealer's Jazz quote in front of you is already a fair one — sometimes it is. Running the comparison on your specific car is the only way to know for certain when compared with results from the panel of brokers.