Financing a Lamborghini Urus in the UK: PCP, HP & Lease Purchase Compared
Author: Terry Hogan
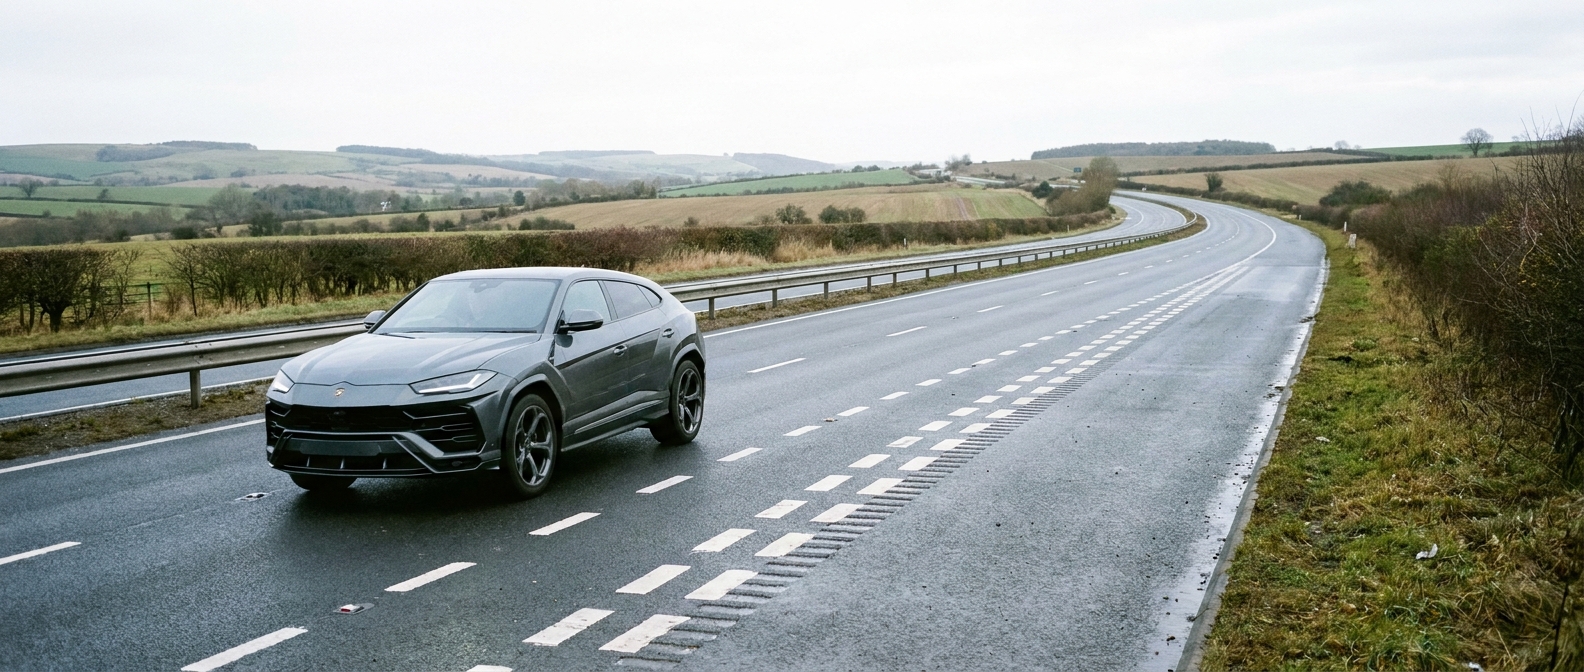
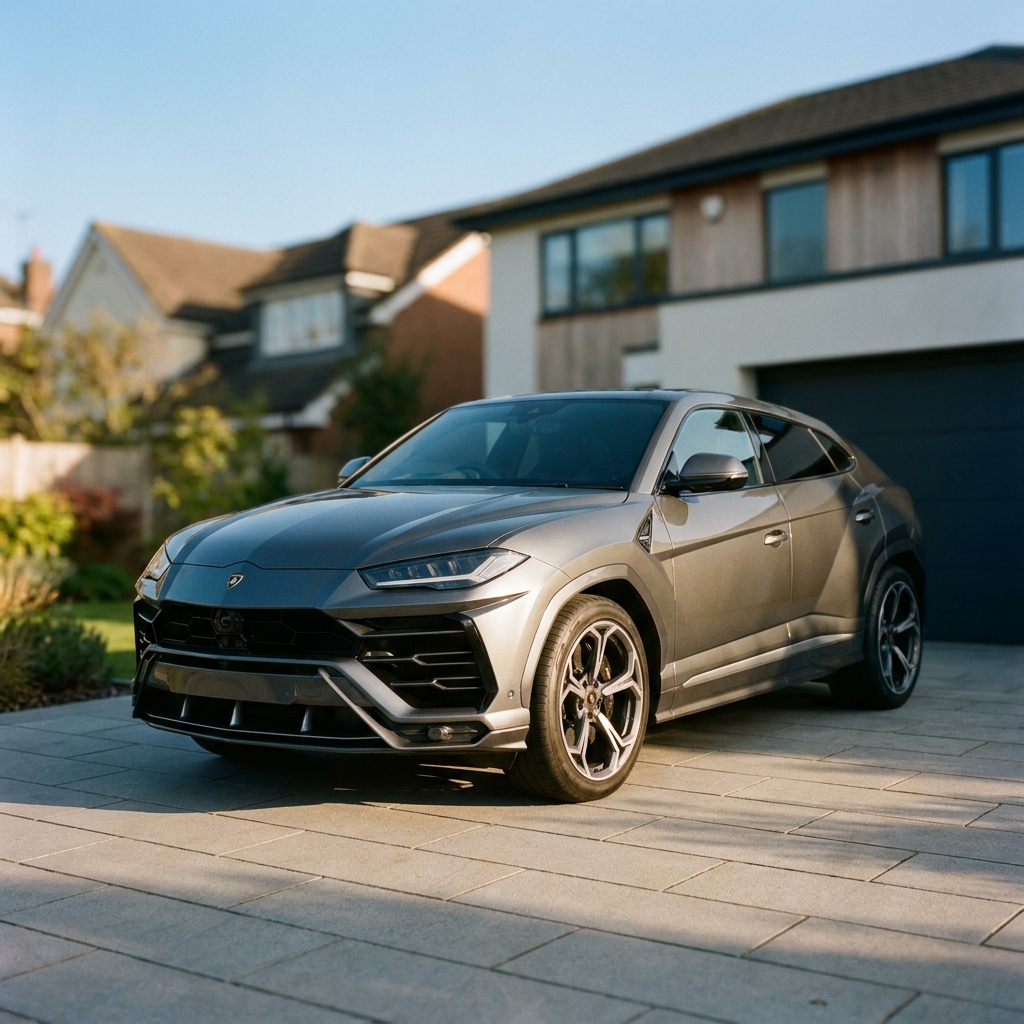
The Lamborghini Urus changed the supercar landscape when it launched in 2018 - proving that a vehicle wearing the raging bull badge could be practical enough for the school run and savage enough to embarrass an entry level Porsche on a B-road. With a 4.0-litre twin-turbocharged V8 producing 650 horsepower (or the newer Urus SE plug-in hybrid extending that to 800 combined horsepower), this is no ordinary SUV. It is, by every measure, a supercar that happens to have five seats and a boot.
With used examples starting from around £130,000 and new models commanding north of £250,000 once options are ticked, few buyers are writing a cheque for the full amount. The vast majority are financing their purchase - and that is where getting the right deal becomes just as important as choosing the right spec.
Having spent over 30 years working in vehicle finance, we have seen how the wrong finance product can cost buyers thousands over the life of an agreement - particularly on high-value vehicles like the Urus, where even a fraction of a percentage point on your APR can translate into significant money. This guide breaks down the three main finance options available to UK buyers, explains how each one works in practice for a car at this price point, and shows you how Prefinance can help you secure a better deal than you would find through a dealer alone.
Who Is Actually Buying a Lamborghini Urus?
Before diving into finance structures, it is worth understanding who typically finances a vehicle like this, because the right product depends heavily on how you plan to use and eventually exit the car.
The typical Urus buyer in the UK tends to fall into one or more of the following categories: high-net-worth individuals, business owners, or entrepreneurs - or a combination of all three. Many are purchasing through a limited company for tax efficiency, and a significant number will already own other prestige or performance vehicles.
Crucially, most Urus buyers are not intending to keep the car for the full duration of a five-year finance term. They like having the latest model, they get bored, or their circumstances change. A buyer who changes cars every two to three years needs a different finance structure from someone who plans to own and keep the vehicle long-term. Understanding this is essential when choosing between HP, PCP, and Lease Purchase.
The Three Main Finance Options for a Lamborghini Urus
There are three principal ways to finance a used Lamborghini Urus through a broker in the UK: Hire Purchase (HP), Personal Contract Purchase (PCP), and Lease Purchase (LP). Each has a different structure, and each produces a different monthly payment and total cost of borrowing. Let's walk through them one by one.
Hire Purchase (HP)
Hire Purchase is the most straightforward form of car finance. You pay a deposit, then make fixed monthly payments over an agreed term (typically three to five years), and at the end of the agreement you own the car outright after paying a small option-to-purchase fee.
The key advantage of HP on a Lamborghini Urus is cost of borrowing. On PCP and Lease Purchase, you effectively pay interest on the amount you borrow AND the balloon. So at the same APR on hire purchase, interest charges are much lower. Because there is no deferred balloon payment, you only pay interest on the balance borrowed. On a vehicle worth £200,000, this is a significant difference in interest.
The trade-off is that your monthly payments will be the highest of the three products, because you are repaying the entire balance across the term with no lump sum deferred to the end. For a Urus buyer on a 48-month HP with a reasonable deposit, monthly payments can comfortably exceed £4,000 depending on rate and deposit.
HP suits Urus buyers who genuinely intend to keep the car, want the cheapest overall cost of finance, and are comfortable with higher monthly outgoings. It is also popular with business owners who wish to claim capital allowances on the full purchase price.
Personal Contract Purchase (PCP)
PCP is the UK's most popular form of car finance, and for good reason - it produces the lowest or second-lowest monthly payments by deferring a large chunk of the balance to a Guaranteed Future Value (GFV) balloon payment at the end of the term.
With PCP on a Lamborghini Urus, the lender predicts what the car will be worth at the end of your agreement (based on age, mileage, and condition) and sets that figure as the GFV. You only make monthly payments on the difference between the car's current value and the GFV, plus interest. At the end of the term, you have three options: pay the balloon and own the car, hand it back with nothing further to pay (subject to mileage and condition), or use any equity as a deposit toward your next vehicle.
The interest rate on PCP is often exactly the same as HP, with our rates starting from 7.9% APR. (Age, mileage and where you are buying the car from can all affect rates) For example, lenders are reticent to lend on private sales, They may do, but at different terms.
There is an important nuance for Urus buyers to understand here. The GFV is guaranteed, which protects you if the market drops, but it is almost always set conservatively - meaning the actual market value of the car at the end of the term is likely to be higher than the GFV. This creates positive equity, which is useful if you plan to trade the car in. However, it also means you are paying interest on the balance to finance and the balloon.
PCP works well for Urus buyers who want manageable monthly payments, expect to change the car before the end of the term, and value the flexibility of being able to hand the car back. It is less ideal if your primary goal is minimising the total amount of interest paid.
Lease Purchase (LP)
Lease Purchase sits between HP and PCP in structure but produces the lowest monthly payments of all three options. Like HP, you pay a deposit and make fixed monthly instalments, with a balloon payment due at the end. The critical difference from PCP is that the balloon is not guaranteed -there is no GFV safety net. You are committed to either paying it or refinancing it at the end of the term.
Because the balloon on a Lease Purchase is not underwritten by the lender, they can set it higher than a PCP's GFV (closer to realistic market value), which in turn means your monthly payments are lower. On a Lamborghini Urus, this can make a substantial difference - monthly payments on LP can be noticeably lower than even PCP, sometimes by several hundred pounds or more.
The risk sits with you. If the car's market value at the end of the term is lower than the balloon figure, you will face a shortfall. On a vehicle like the Urus, which has historically held its value well relative to other luxury SUVs, many buyers consider this an acceptable risk. But it is a risk nonetheless, and one you should go into with your eyes open.
Lease Purchase is particularly popular with business owners and high-net-worth individuals who are confident in the residual value of the car, want the lowest possible monthly cost, and are comfortable managing the balloon at the end - whether that means refinancing, settling outright, or part-exchanging.
HP vs PCP vs Lease Purchase on a Lamborghini Urus
The table below provides a side-by-side comparison of the three main finance products as they apply to a high-value vehicle like the Lamborghini Urus. These are general characteristics - actual rates and payments will vary depending on the vehicle, your deposit, term, credit profile, and the lender.
Feature | Hire Purchase (HP) | PCP | Lease Purchase (LP) |
|---|---|---|---|
Monthly Payments | Highest | Medium | Lowest |
Interest Rate (APR) | Low | Low | May be a little higher |
Balloon / Final Payment | None (or very small option-to-purchase fee) | Yes - Guaranteed Future Value (GFV) set by lender | Yes -often higher balloon, not guaranteed |
Total Interest Paid | Lowest | Higher (interest charged on full balance and GFV) | Higher (interest charged on full balance and balloon) |
Ownership at End of Term | Yes, automatic after final payment | Optional - pay the GFV to own, hand back, or part-exchange | Must pay or refinance the balloon to own. No hardback option |
Downside Protection | N/A - you own the car | GFV protects you if market value falls below the guaranteed figure | No protection - if market drops below balloon, you face a shortfall |
Flexibility to Change Car Early | Can settle and sell at any time, but no built-in hand-back option | Can hand back at end of term; can settle early and use equity to change | Can settle early but must clear balloon; no hand-back option |
Mileage Restrictions | None | Yes - excess mileage charges apply if you hand vehicle back only | Typically none |
Best Suited To | Buyers who want to own long-term and minimise total cost | Buyers who change cars regularly and want flexibility | Buyers who want lowest monthly cost and are comfortable managing the balloon |
Business Use / Tax | Capital allowances may be claimable, but depends on new/used. Check with your advisor | Capital allowances may be claimable, interest deduction available | Capital allowances may be claimable. Interest deduction available |
Typical Availability for Urus | Available from selected lenders | Available on newer vehicles up to around 6 years old | Specialist product - fewer lenders but flexible on age. Cases are often individually priced. |
How Prefinance Helps You Get a Better Deal
This is where the process of actually securing your finance matters just as much as choosing the right product.
Prefinance is a car finance comparison service — not a broker and not a lender. What we do is compare deals from multiple specialist finance brokers, each of whom works with their own panel of lenders. The result is that you see a wider range of rates and products than you would find by approaching any single broker or dealer.
Why does this matter for a Lamborghini Urus? Because dealer finance on prestige vehicles is often significantly more expensive than what the open market can offer. Based on our recent user data, the average representative APR offered by dealers for a used Lamborghini Urus is approximately 11.1%. Through Prefinance, rates start from 7.9% (representative 8.9% APR), and our users save an average of £241 per month - which adds up to an average total saving of approximately £11,590 over the life of the agreement.
Those are not theoretical figures. They come from real comparisons made by real users on our platform.
Here is how the process works in practice. You tell us about the vehicle you are looking to finance — the make, model, price, and your preferred deposit and term. Our technology compares your enquiry across our panel of specialist brokers, each of whom can access competitive rates from multiple lenders. You receive quotes you can compare side by side, with no impact on your credit score (we use a soft credit check at the comparison stage). You then choose the deal that works best for you and proceed directly with the broker.
We built Prefinance because, after more than three decades in the motor finance industry, we know that the difference between a good deal and a poor one is rarely about the car — it is about who you speak to and how many options you actually see before committing. Most buyers only ever see the dealer's offer. Our service exists to change that.
Choosing the Right Finance Product for Your Urus
There is no single "best" finance product — only the one that best fits your circumstances, your plans for the car, and your appetite for risk. Here is a practical way to think about it.
If you want to own the car outright and your priority is paying the least total interest, HP is your product. You will pay more each month, but you will pay less overall, and the car is yours at the end with no balloon to worry about.
If you like to change cars every two to three years (as many Urus buyers do), value the flexibility of being able to hand the car back, and want a guaranteed floor price protecting you against market drops, PCP gives you that safety net — at the cost of a higher rate and more total interest.
If your priority is the absolute lowest monthly payment and you are confident the Urus will hold its value (or you have the means to manage the balloon regardless), Lease Purchase delivers the cheapest monthly cost. Just be aware that the balloon is your responsibility, and there is no guaranteed buy-back figure to fall back on.
For business owners, the tax treatment of each product also warrants consideration. HP and Lease Purchase typically allow you to claim capital allowances on the full purchase price of the vehicle, while PCP can be more complex depending on whether you intend to exercise the option to purchase. We would always recommend speaking to your accountant about which structure is most tax-efficient for your specific situation.
What to Watch Out For
A few practical points worth keeping in mind when financing a vehicle at this price level.
First, not all lenders will finance a Lamborghini Urus. It is a high-value, niche vehicle, and some lenders have caps on the amount they will lend or restrictions on the age and mileage of vehicles they will consider. This is one of the reasons using a comparison service like Prefinance is so valuable — our broker panel includes specialists who work with prestige and high-value vehicles day in, day out.
Second, be cautious about the deposit. Putting down a larger deposit reduces your monthly payments and total interest, but on a depreciating asset it also increases your exposure if the car is written off or stolen early in the agreement. GAP insurance is worth considering on any Urus finance deal.
Third, check whether the finance agreement includes mileage restrictions (PCP will; HP and LP typically will not). Urus buyers who use the car as a daily driver may find PCP mileage limits restrictive, and excess mileage charges at the end of a PCP agreement can be punitive.
Finally, always check the total amount payable — not just the monthly figure. A lower monthly payment achieved through a longer term or higher rate may end up costing you significantly more in total. This is where comparing like-for-like quotes side by side, as Prefinance enables you to do, really pays dividends.
Ready to Compare Urus Finance Deals?
If you are considering financing a Lamborghini Urus, start by comparing what is actually available to you — not just what the dealer puts in front of you. Prefinance lets you compare quotes from multiple specialist brokers in minutes, with no impact on your credit score. Our users save an average of £241 per month on Lamborghini Urus finance compared to dealer rates, and with over 30 years of motor finance expertise behind the service, you can be confident you are seeing the full picture before you commit.
Visit prefinance.co.uk to get started, or explore our Lamborghini Urus finance deals page for current rates and options.
Prefinance is a car finance comparison service, not a broker or lender. We work with a panel of specialist finance brokers who can offer competitive rates from 7.9% APR (representative APR 8.9%). Finance is subject to status. UK residents aged 18 and over only. Rates shown are best available and may not be available for the car you have chosen due to your credit history, lender changes, age of vehicle, mileage of vehicle, private sales etc.