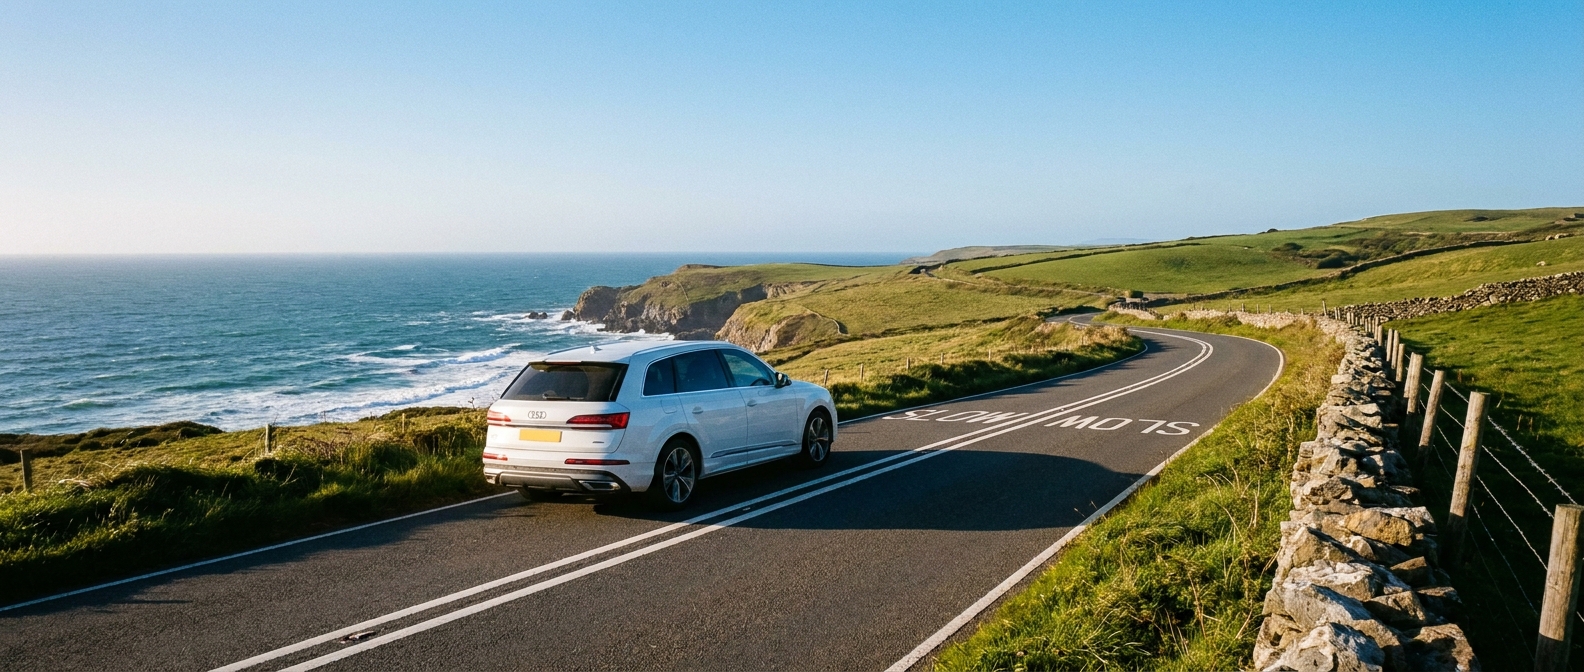
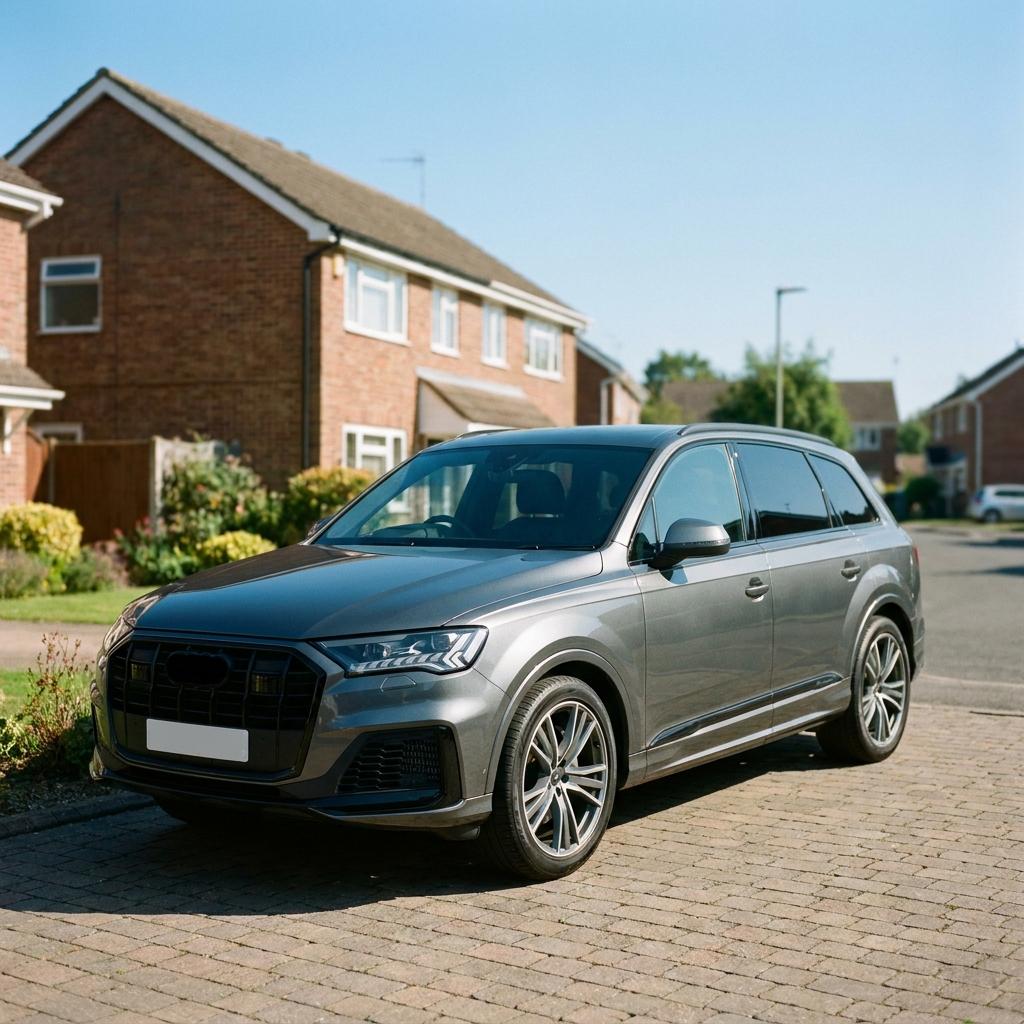
The Audi Q7 is a luxurious and capable SUV, perfect for families or those who appreciate a commanding presence on the road. It's a big, 7 seater car! If you're considering adding one to your driveway, understanding your finance options is key. At Prefinance, we help you compare various car finance products to find a deal that suits your budget and lifestyle, ensuring you get behind the wheel of your desired Audi Q7 without overpaying.
Q7 Finance Options
When financing an Audi Q7, you'll typically encounter two main types of finance products: Personal Contract Purchase (PCP), Hire Purchase (HP), and possibly a third, Lease Purchase. Each offers distinct advantages, and the best choice for you depends on your priorities.
Looking into how these options work, you can explore our comprehensive guide to Audi on Finance.
Personal Contract Purchase (PCP) for your Audi Q7
With PCP, your monthly payments are based on the depreciation of the car's value over the finance term, rather than its full purchase price. This often results in lower monthly instalments compared to HP.
Here's how it generally works:
You pay an initial deposit.
You make fixed monthly payments over an agreed term (typically 2-4 years).
A significant portion of the car's value is deferred to the end of the agreement as an optional final payment, also known as the Guaranteed Minimum Future Value (GMFV) or balloon payment.
At the end of the PCP agreement, you have three choices:
Return the Q7: Provided you've kept within the agreed mileage and condition, you can simply hand the car back and walk away without further obligation.
Pay the optional final payment: If you love your Audi Q7 and want to own it outright, you can pay the GMFV.
Part-exchange for a new car: You can use any equity (if the car's market value is higher than the GMFV) towards a deposit on your next vehicle.
PCP offers flexibility and lower monthly costs, making a premium SUV like the Audi Q7 more accessible. Learn more about PCP Car Finance Explained.
Hire Purchase (HP) for your Audi Q7
If outright ownership is your ultimate goal, Hire Purchase might be a more suitable option. With HP, you essentially hire the car over the finance term, and once all payments, including an 'option to purchase' fee, have been made, you become the legal owner.
Key features of HP include:
You pay an initial deposit.
You make fixed monthly payments over an agreed term (typically 2-5 years), although longer terms can be available from some lenders.
There is no large final balloon payment, as you're paying off the full value of the car (minus your deposit) over the term.
While monthly payments for HP are often higher than PCP for the same car and term, you gain ownership at the end of the agreement without any further lump sum payment. This can be particularly appealing if you plan to keep your Audi Q7 for many years.
Lease Purchase for your Audi Q7
Lease Purchase is a less common option but can be beneficial for some. It combines elements of both HP and PCP. Similar to PCP, it features lower monthly payments due to a deferred lump sum payment at the end of the agreement. However, unlike PCP, there is no mileage restriction, and you are generally committed to purchasing the vehicle at the end of the term by paying the final balloon payment.
This option is often favoured by businesses or individuals who are certain they want to own the vehicle but prefer lower monthly outgoings during the finance period.
For us, it feels like an option for some of the real high end SQ7s, but as the Q7 isn't amazing at holding it's value (from new anyway), there aren't many cars this option would suit. Think 3 year old SQ7, business owner, wanting low payments.
How Prefinance Helps You Save on Audi Q7 Finance
At Prefinance, we're dedicated to helping you find competitive finance deals for your Audi Q7. We are a comparison service, not a lender or broker ourselves. We connect you with specialist finance brokers who can access a wide panel of lenders, often securing rates from 7.9% APR (representative APR 8.9%).
Comparing finance options through Prefinance can lead to significant savings. Our data shows that customers financing an Audi through our service save, on average, £59.26 per month, totalling an average saving of £2,738.09 over the finance term compared to typical dealer finance rates. This is because we enable you to compare multiple offers, ensuring you don't settle for the first deal you're presented with.
To see how much you could save, consider getting a car finance quote through our platform.
Why Compare with Prefinance?
Choosing Prefinance to compare your Audi Q7 finance options offers several advantages:
Access to Specialist Brokers: We work with experienced finance brokers who understand the market and can find deals tailored to your circumstances.
Competitive Rates: Our specialist brokers offer rates from 7.9% APR (representative APR 8.9%), often beating standard dealer offers.
Time-Saving: Instead of approaching multiple lenders yourself, our service allows you to compare various offers quickly and efficiently.
Transparent Process: We aim to make car finance clear and understandable, helping you make an informed decision.
No Obligation: Getting a quote through Prefinance doesn't commit you to anything. You're free to review your options and decide what's best.
Understanding the potential savings is crucial when making a significant purchase like an Audi Q7. Here's a look at average savings our customers experience when financing an Audi:
Make | Prefinance Avg. APR | Dealer Avg. APR | Avg. Monthly Saving | Avg. Total Saving |
|---|---|---|---|---|
Audi | 8.81% | 12.12% | £59.26 | £2,738.09 |
These figures, based on a sample size of 311 Audi finance applications, highlight the tangible benefits of comparing finance options before committing. For more insights into finding the best deals, read our guide on Finding the Best Car Finance Deals in the UK.
Factors Affecting Your Audi Q7 Finance Deal
Several factors will influence the finance deal you're offered for an Audi Q7. Understanding these can help you prepare and potentially secure a more favourable rate.
Your Credit Score
A strong credit history is vital for securing the most competitive finance rates. Lenders use your credit score to assess your reliability as a borrower. The better your credit score, the lower the interest rate you're likely to be offered. It's a good idea to check your credit report before applying for finance to ensure accuracy and identify any areas for improvement.
Deposit Amount
The size of your initial deposit can significantly impact your monthly payments and the total interest you pay. A larger deposit means you're borrowing less, which can lead to lower monthly instalments and potentially a better APR. While there's no fixed rule, consider how much deposit you're comfortable putting down. You can find more information on this in our article: How Much Deposit Should I Put Down for Car Finance?
Finance Term
The length of your finance agreement (the term) also plays a role. Longer terms generally result in lower monthly payments, as the cost is spread over a greater period. However, a longer term often means you'll pay more interest overall. Conversely, a shorter term will have higher monthly payments but less total interest paid. It's about finding a balance that fits your budget and long-term financial goals.
Vehicle Age and Value
The age and value of the Audi Q7 you choose will affect your finance options. Newer, more expensive models typically command higher finance amounts. Used cars can sometimes offer more flexible finance terms, though the interest rates might vary depending on the lender's policies for older vehicles. Prefinance can help you find finance for both new and used Audi Q7 models.
Comparing Finance Products: PCP vs. HP for your Audi Q7
Deciding between PCP and HP is a common dilemma for car buyers. Here's a quick comparison to help you weigh the options for your Audi Q7:
Feature | Personal Contract Purchase (PCP) | Hire Purchase (HP) |
|---|---|---|
Ownership | Optional at end of term (via balloon payment) | Automatic at end of term (after final payment) |
Monthly Payments | Typically lower (based on depreciation) | Typically higher (paying off full car value) |
End of Agreement Options | Return, buy, or part-exchange | Own the car |
Mileage Restrictions | Yes (affects GMFV if exceeded) | No |
Ideal For | Those who like to change cars frequently, prefer lower monthly costs | Those who want to own the car outright, don't mind higher monthly costs |
For a more detailed comparison, refer to our article on PCP vs HP Car Finance.
Your Next Steps to Financing an Audi Q7
Financing an Audi Q7 doesn't have to be complicated. By understanding your options and comparing deals, you can secure a finance package that works for you. Prefinance is here to simplify this process, connecting you with specialist brokers who can help you find competitive rates from 7.9% APR (representative APR 8.9%).
Ready to explore your Audi Q7 finance options? Get a quote through Prefinance today and see how much you could save on your next luxury SUV. It's quick, easy, and could make a significant difference to your monthly budget.