If you're considering a Range Rover, understanding the finance options available and knowing how to compare payments using our Range Rover Finance Calculator helps you make a better decision. This guide will walk you through the popular ways to finance a Range Rover in the UK, help you understand the rates, products and their pros and cons.
Range Rover Finance Options
When it comes to financing a Range Rover, you'll typically encounter three main products: Personal Contract Purchase (PCP), Hire Purchase (HP), and Lease Purchase. Each has features that can impact your monthly payments, ownership prospects, and overall cost. Let's explore:
Personal Contract Purchase (PCP) for a Range Rover
PCP is a popular choice for those who enjoy changing their car every few years. It's designed to offer lower monthly payments compared to HP, as you're not financing the entire value of the car. Here’s how it works:
You pay an initial deposit.
Your monthly payments cover the depreciation of the car over the contract term, plus interest.
A significant portion of the car's value is deferred to the end of the agreement as an optional final payment, often called a Guaranteed Minimum Future Value (GMFV) or balloon payment.
At the end of the PCP agreement, you have three choices:
Return the car: Hand the car back to the finance company, provided you've stayed within the agreed mileage and kept it in good condition.
Buy the car: Pay the optional final payment to own the Range Rover outright.
Part-exchange: Use any equity (if the car is worth more than the optional final payment) towards a deposit on a new car.
PCP can make a Range Rover more accessible due to lower monthly outgoings, but it's important to consider the mileage limits and the optional final payment if you intend to own the vehicle.
You can learn more about this popular finance option in our comprehensive guide: PCP Car Finance Explained.
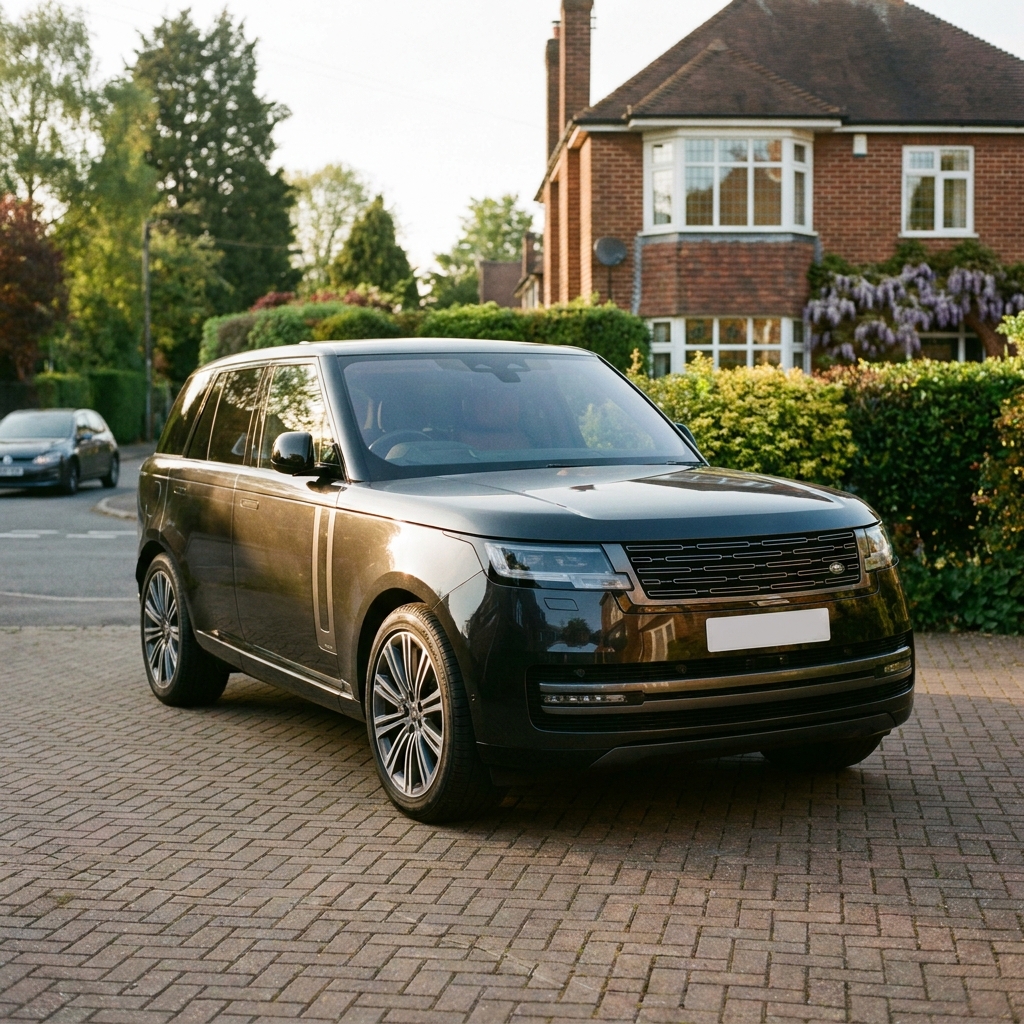
Range Rover builds 4 models for the UK market. The luxury full-sized Range Rover, the Sport, The Mid-Sided Velar, and the more compact Evoque.
A 3-year-old Range Rover SE starts from around £65,000 as it stands today. On a PCP with a 10% deposit, that's a sub-£900 payment (just!) and a balloon of just under £29,800. Whilst that's a reasonably high payment, it's a lot lower than hire purchase for the same term.
A 3-year-old Range Rover Velar starts from around £25,000 for a diesel 2.0 D200 MHEV R-Dynamic S Auto 4WD Euro 6 (s/s) 5dr. Comparing dealer rates to Prefinance could save you a small fortune. With a 10% deposit, payments come in at under £400 with a £9,375 balloon.
On to the Range Rover Sport. Because of its desirability, a 3-year-old Range Rover Sport Dynamic SE has a price tag from around £55,000, so PCP payments come in around £720 with a 10% deposit and a £27,509 balloon.
You can find deals on Evoques here https://prefinance.co.uk/best-finance-deals/land-rover/range-rover-evoque
Hire Purchase (HP) for Range Rovers
Hire Purchase is a straightforward route to ownership. With HP, you essentially hire the car until all payments are made, at which point you become the legal owner.
You pay an initial deposit.
Your monthly payments cover the entire cost of the car, plus interest, which is spread over the agreement term.
Once all payments, including a small 'option to purchase' fee, are made, the car is yours.
HP agreements typically have higher monthly payments than PCP because you're financing the full value of the vehicle. However, there are no mileage restrictions or large final payments to worry about, making it ideal if you plan to keep your Range Rover for the long term. For a detailed comparison, see our article on PCP vs HP Car Finance.
Lease Purchase for Range Rovers
Lease Purchase is a less common but viable option, particularly for higher-value vehicles like a Range Rover. It shares similarities with both PCP and HP:
It involves an initial deposit and fixed monthly payments over a set term.
Like PCP, a significant balloon payment is deferred to the end of the agreement.
Unlike PCP, there is no Guaranteed Minimum Future Value (GMFV), meaning the final payment is not guaranteed, and you are obligated to make this payment to own the car.
Lease Purchase is generally suited for those who are confident in the car's residual value and intend to own the vehicle at the end of the term, or for businesses looking for specific accounting benefits.
Here's a quick comparison of the key features of these finance products:
Feature | PCP | HP | Lease Purchase |
|---|---|---|---|
Ownership at end | Optional (via final payment) | Yes (after all payments) | Yes (via final payment) |
Monthly payments | Lower | Higher | Lower (due to balloon) |
Final payment | Optional (GMFV) | Small 'option to purchase' fee | Obligatory balloon payment |
Mileage restrictions | Yes | No | No |
Suitability | Regular upgrades | Long-term ownership | Ownership with lower payments/Business Users and HNW |
Competitive Range Rover Finance Deals
The cost of financing a Range Rover can vary significantly depending on the lender, your credit profile, and the specific finance product. Prefinance is a comparison service that helps you navigate the market to find competitive deals from specialist finance brokers. We work with brokers who can offer rates with a representative APR of 8.9%.
Factors Affecting Your Finance Rate
Several elements influence the interest rate you'll be offered for your Range Rover finance:
Credit Score: A strong credit history demonstrates reliability and can lead to better rates.
Deposit Amount: A larger upfront deposit can reduce the amount you need to borrow, potentially lowering your monthly payments and overall interest paid. Find out more about how much deposit you should put down.
Loan Term: Shorter loan terms often come with higher monthly payments but less interest paid overall, while longer terms spread the cost but can accumulate more interest.
Vehicle Age: Newer vehicles sometimes attract slightly better rates due to their predictable depreciation.
By comparing offers from various specialist brokers, you can ensure you're getting a finance package that's tailored to your circumstances and offers good value. Prefinance simplifies this process, allowing you to see multiple options in one place without impacting your credit score with multiple applications
New vs Used Range Rover Finance
Whether you're looking for a brand-new Range Rover or a pre-owned model, finance options are available for both. The choice between new and used often comes down to budget, desired features, and depreciation considerations.
Financing a New Range Rover
New Range Rovers offer the latest technology and features, and often come with manufacturer warranties. Financing a new model typically means:
Access to the latest models such as the Range Rover Sport, Evoque, Velar, or the flagship Range Rover.
Potentially lower APRs from manufacturer-backed finance deals (though Prefinance helps you compare against specialist brokers too).
The steepest depreciation occurs in the first few years, which is a key factor in PCP agreements. Most of our clients are financing used cars and this is our speciality, but we do finance new vehicles where the manufacturer terms are not suitable
When considering a new Range Rover, it's always wise to compare offers from various sources, not just the dealership. Prefinance can help you see if a specialist broker can offer a more competitive rate for your chosen new vehicle.
Financing a Used Range Rover
A used Range Rover can offer significant savings on the initial purchase price, making luxury more attainable. When financing a used model:
You benefit from the initial depreciation having already occurred.
A wider range of models and specifications might be available within your budget.
Finance terms might be slightly shorter for older vehicles, or the interest rate could be marginally higher, depending on the lender's criteria.
Prefinance specialises in helping customers find finance for used cars, connecting you with brokers who understand the used car market. Whether it's a nearly new model or one a few years old, comparing options is key to securing a favourable deal.
Why Compare Range Rover Finance with Prefinance?
Prefinance isn't a broker or a lender; we're a comparison service designed to put you in control. Our goal is to help you find competitive Range Rover finance deals by comparing offers from a panel of specialist finance brokers. Here's why that matters:
Save Time: Instead of approaching multiple lenders individually, you get multiple offers in one place.
Save Money: By comparing, you increase your chances of finding a lower APR and better terms, potentially saving you thousands over the life of the agreement.
Expert Brokers: We connect you with specialist brokers who understand the nuances of car finance and can tailor solutions to your needs.
No Impact on Credit Score: Our initial comparison process won't affect your credit rating.
Transparent & Trustworthy: We provide clear information to help you understand each offer, without the jargon.
Whether you're looking for a new Range Rover or a quality used model, comparing your finance options is a smart move. Prefinance makes it simple to explore what's available and find a deal that fits your budget. Start comparing Range Rover finance deals today, and take the first step towards driving your ideal luxury SUV.