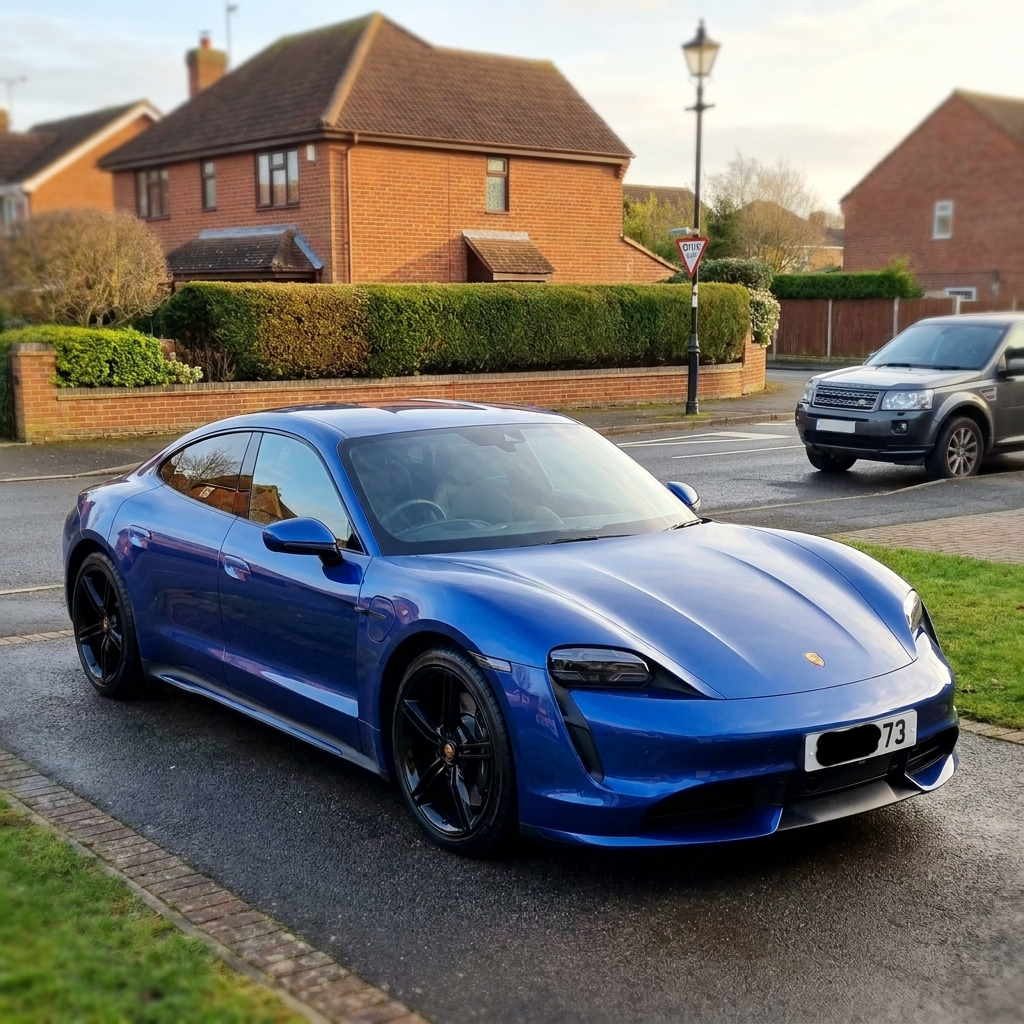
The Porsche Taycan has reshaped what people expect from an electric car. It looks, drives, and feels like a Porsche - which is precisely why used examples are now some of the most sought-after EVs on the market, especially now prices have reset to lower levels on the older models Prices for used Taycans starting from around £30,000 for early base models and rise beyond £120,000 for Turbo S variants, so financing is the practical route for most buyers. But there's a catch: dealer finance on a used Taycan isn't always competitive, and the rates Porsche Centres quote on approved used stock can be beaten if you know where to look. This guide covers the main used Porsche Taycan finance options, explains how rates stack up, and shows how Prefinance helps you compare deals from multiple specialist brokers to find something better.
Used Porsche Taycan Finance: Your Three Main Options
Whether you're after a rear-wheel-drive Taycan, a 4S, or a Turbo, the same three finance products are available to UK buyers: PCP, HP, and Lease Purchase. Each works differently, and the best fit depends on how long you plan to keep the car and how much you want to pay each month.
Porsche Taycan PCP Deals
PCP keeps your monthly payments manageable by deferring a portion of the car's value - the Guaranteed Future Value (GFV) - as a final balloon payment. You pay a deposit, make fixed monthly instalments covering depreciation and interest, and at the end of the term you choose: pay the balloon, hand the car back (subject to mileage and condition terms), or use any equity toward your next vehicle. PCP is popular with Taycan buyers who expect to upgrade to a newer model in two to four years, especially as EV technology evolves rapidly.
There's a specific consideration with Taycan PCP that's worth noting. EV residual values have been less predictable than petrol equivalents over the past few years. Lenders factor this uncertainty into the GFV, often setting it conservatively. That means your monthly payments may be slightly higher than you'd expect for a car at this price point, because the lender isn't willing to guarantee as much of the future value.
Hire Purchase (HP)
HP spreads the full purchase price across your monthly payments with no balloon. You pay more each month, but the total interest is lower and the car is yours once the agreement ends. This suits Taycan buyers who plan to keep the car for the long term - perhaps those running lower annual mileage or buying a specific variant they've wanted for a while.
Lease Purchase
Lease Purchase works like HP but with a final balloon payment that isn't guaranteed by the lender. The balloon is typically set higher than a PCP's GFV, keeping your monthly costs lower. It's a more specialist product, and fewer lenders offer it for EVs. But for a Taycan buyer who is confident in the car's residual value and wants the lowest possible monthly outgoing, it's worth exploring through the right broker.
Lease purchase is aimed at HNW individuals and business owners. It's not a regulated agreement either, so you get fewer baked-in consumer rights than on PCP and no guarantee on the residual value.
For nearly new Taycans that still qualify for the 100% capital allowance, a business owner could potentially write down the whole value of the car against taxable profits, and the interest on the loan too, making a chunky saving on the price. Check with your accountant for current HMRC rules on allowances and eligibility, or visit the HMRC website.
How Taycan Finance Rates Compare
Porsche's own approved used programme currently quotes a representative 9.9% APR on Taycan models. Independent dealers and third-party finance arms typically sit between 10% and 12%. Through Prefinance, the specialist brokers we compare offer rates starting from 7.9% APR on Taycans valued above £40,000 (representative 8.9% APR). Most used Taycans on the market fall comfortably above that threshold.
Finance Source | Typical APR (Used Taycan) | How It Works |
|---|---|---|
Porsche Financial Services (Approved Used) | 9.9% representative | Single lender, Porsche Centre only |
Independent Dealer Finance | 10% – 12% | Usually one or two lenders available |
Specialist Broker (single) | 8% – 10% | Access to their own lender panel |
Prefinance (comparison service) | From 7.9% (rep. 8.9%) | Compares quotes from multiple specialist brokers |
The practical difference is significant. On a used Taycan 4S priced at £65,000 with a 10% deposit, the gap between 7.9% and 9.9% APR over 48 months adds up to roughly £2,400 in additional interest at the higher rate. Our data across all Porsche models shows that Prefinance users save an average of £86.50 per month compared to dealer finance - a total average saving of £4,072 over the life of the agreement.
Things to Consider When Financing a Used Taycan
Battery and Warranty
Porsche's Taycan battery warranty runs for eight years or 100,000 miles from original registration, which provides reassurance for used buyers. This warranty transfers with the car, not the owner - so even a privately purchased used Taycan benefits. Finance lenders factor warranty status into their risk assessment, and a car still within its battery warranty period will generally attract better terms.
Depreciation Patterns
Early Taycans depreciated more steeply than many expected, partly due to rapid EV market expansion and lower range, and also competition from more market entrants. That depreciation has now largely stabilised, and used values are firmer than they were 18 months ago. For PCP buyers, this matters because it affects both the GFV the lender sets and the equity position you'll be in at the end of your term.
Which Taycan Model Offers the Best Value on Finance?
The Taycan 4S sits in a sweet spot for many Porsche finance buyers. It offers strong performance (up to 571 PS with overboost in Performance Battery Plus spec), reasonable used values in the £32,000–£75,000 range, and enough demand to support competitive PCP residuals. The base Taycan is cheaper to finance. Turbo and Turbo S models command higher prices and can attract buyers who are comfortable with Lease Purchase or HP rather than PCP.
Why Compare Taycan Finance Before You Buy?
Most used Taycan buyers visit a Porsche Centre or independent specialist, find the car they want, and accept whatever finance is offered on the spot. The problem with this approach is that you're seeing a single quote from a single source. Prefinance works differently - we compare deals from multiple specialist brokers, each with access to their own panel of lenders. You see the rates side by side, choose the one that fits, and proceed directly with that broker. There's no impact on your credit score at the comparison stage, and no obligation to proceed.
On a car that costs £60,000 or more, even a modest rate reduction saves you real money. That's the whole point of comparing: you buy the same car, from the same dealer, at the same price - but you pay less for the finance.
Compare Used Porsche Taycan Finance Deals
If you've got a Taycan in mind - or you're weighing it against the 911 or 718 Cayman - start by comparing your finance options. Visit the Porsche Taycan finance deals page on Prefinance to see what rates are currently available from our panel of specialist brokers. Rates start from 7.9% APR on vehicles over £40,000. No hard credit check, no obligation, and it takes minutes.
Prefinance is a car finance comparison service, not a broker or lender. We work with a panel of specialist finance brokers who can offer competitive rates from 7.9% APR (representative APR 8.9%). Finance is subject to status. UK residents aged 18 and over only.